
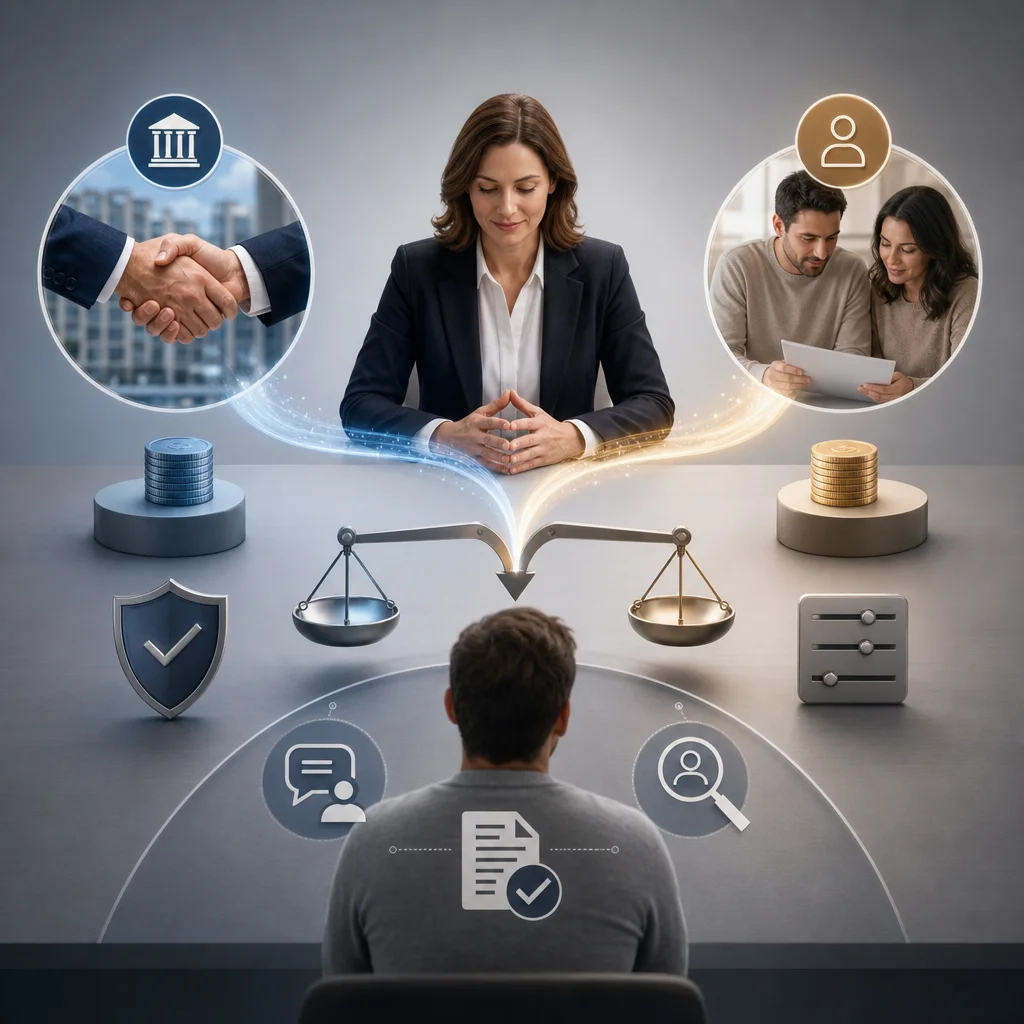
Credit brokers can be paid by lenders, customers or both. The commercial model can be legitimate and useful, but the firm must explain its role, disclose charges and commission when required, and control the incentives created by the payment.
This guide focuses on UK consumer credit broking. The application of individual rules depends on the activity, agreement and customer; mortgage and other specialist regimes need separate consideration.
A credit broker does not usually lend the money. It connects a customer with a lender or another broker, helps with an application, and may provide advice or a recommendation where its service includes that step. Revenue follows that work. The broker may receive a fee from the lender, charge the customer, or use both sources.
For the distinction between providing credit and arranging it, see our credit broker versus lender guide.
The payment route matters because it can influence which products the broker presents, how prominently it presents them and what the customer ultimately pays. Commission is not automatically improper, and a customer fee is not automatically clearer. The compliance question is whether the customer understands the service and its cost, while the firm identifies and manages the conflicts created by its remuneration model.
A lender may pay the broker for a click through, an introduction, a completed credit agreement, or a percentage of the amount financed. Some arrangements also include volume bonuses or payments linked to the performance of a portfolio. The FCA's current regulatory returns recognise several of these categories, and its published income guidance treats commissions, fees, administration charges and volume bonuses as credit broking income where they relate to regulated activity. These categories are not an endorsement of every payment arrangement: relevant restrictions and the work performed still matter.
This model allows the customer to use the brokerage service without paying a separate broker invoice. That does not make the service economically free. A lender payment may still influence the broker's panel, product ranking or recommendation. It may also affect the amounts payable under the credit agreement, depending on how the arrangement works.
A broker may charge an application, administration, arrangement or success fee. Calling the payment a membership charge or web registration fee does not take it outside the FCA's credit broking fee rules. CONC 4.4 treats a charge broadly, including financial consideration payable to the firm or a third party.
A customer fee can support a service that requires significant work or specialist access. It also creates an obvious value question. The firm should be able to show what the customer receives, why the charge is proportionate and whether customers who do not obtain credit receive the refund to which they are entitled.
Some brokers receive commission from a lender and charge the customer as well. A combined model is not automatically prohibited, but it raises the disclosure and conflict stakes. The firm needs a complete view of all remuneration connected with the transaction. It should assess whether the customer receives fair value, whether lender payments could affect the options offered, and whether staff incentives favour the firm's income over the customer's needs.
| Revenue model | Typical trigger | Main customer risk | Key control |
|---|---|---|---|
| Lender paid | Lead introduction or completion | Panel ranking or recommendation follows commission | Map commission and test selection outcomes |
| Customer paid | Application service or successful outcome | Unclear charge poor value or missed refund | Use the prescribed notice confirmation and refund process |
| Combined | Customer fee plus lender remuneration | Total reward is obscured or incentives compound | Assess total remuneration value and conflicts together |
Financial promotions must make clear when a firm is acting as a credit broker and not a lender. The wider service description should also be accurate. Under its Consumer Duty guidance for credit brokers, the FCA says relevant information may include whether the customer will receive advice or a recommendation, how many lenders the broker has arrangements with, and whether the broker receives lender commission.
A claim to search the market, find the best deal or act impartially must match the panel and the selection process. If the service considers only a limited number of lenders, that limitation should be clear enough for the customer to understand what the broker is and is not doing.
CONC 4.4 requires the broker to disclose any fee payable by the customer. The customer and broker must agree the fee, with that agreement recorded in writing or another durable medium before the regulated credit agreement is entered into. The broker must explain how and when the fee is payable and when a refund may be available. It must also tell the lender about the fee so the lender can calculate the APR correctly.
Before requesting payment or asking for card or payment details for the purpose of collecting the charge, the broker must send a compliant information notice in a durable medium and receive the customer's confirmation in a durable medium. The notice includes the firm's legal name, its broker status, the amount or calculation basis of the charge, and when and how payment will be taken. A link to a webpage is not enough. The firm must keep the notice and confirmation, and each fee charging broker in a chain has its own obligation. CONC 4.4.4R provides a specific exception to this information-notice rule where the customer seeks credit secured on land and the firm makes clear it will broker only that kind of credit. Firms should check the precise conditions; the exception does not remove other applicable disclosure obligations.
CONC 4.5.3R is conditional rather than a blanket rule for every payment. A broker must prominently disclose, in good time before the agreement, the existence and nature of commission or other remuneration from a lender, owner or third party where its existence or amount could actually or potentially affect the broker's impartiality, or would materially affect the customer's decision if known.
Where that disclosure is required, the broker must give equal prominence to how the commission's existence and nature may affect the amounts payable by the customer. Variable remuneration and differences between products or lenders are circumstances addressed by the FCA's disclosure guidance. If the customer asks, CONC 4.5.4R requires disclosure of the amount, or likely amount if the exact figure is not known, in good time before the regulated credit or consumer hire agreement is entered into.
A technically present disclosure can still fail to support customer understanding. The FCA expects information about commission to arrive at the right time, be easy to identify and help the customer make an informed decision. Small print at the end of a journey is unlikely to do that job where commission is important to the choice. Firms should test whether customers notice and understand the explanation, then monitor the outcome after launch.
Section 155 of the Consumer Credit Act and CONC 6.8 can entitle a customer to recover a brokerage fee, less £5, where the relevant credit agreement is not entered into within six months of an introduction. The FCA expects refund requests to be handled promptly. A forecast that treats every fee as final income without allowing for refunds is both commercially weak and a warning sign for customer support. Where section 155 applies, CONC 6.8.4AR also requires the firm to bring the refund right and how to exercise it to the customer's attention as soon as reasonably practicable after the six-month period. FCA guidance indicates five working days would be reasonably practicable.
The current motor finance position shows why disclosure must describe the real commercial arrangement. In August 2025, the Supreme Court largely overturned the Court of Appeal's broader judgment in the joined Johnson cases, but it confirmed that inadequate commission disclosure can contribute to an unfair relationship under the Consumer Credit Act. The FCA identifies relevant factors including the size and nature of commission, the customer's characteristics, compliance with regulatory rules, and the extent and manner of disclosure.
The FCA established a motor finance consumer redress scheme in March 2026. Parts of the scheme were suspended by the Upper Tribunal in July during legal challenges, while firms remained required to follow the rules that were not suspended. That scheme is specific to motor finance and historic arrangements. The broader lesson is relevant to every broker: a generic statement that commission may be received does not cure a business model that the customer would understand differently if the material facts were clear. Separately, the ban on motor-finance discretionary commission arrangements under CONC 4.5.6R remains important: disclosure cannot make a prohibited arrangement permissible.
Disclosure is one control, not the whole control framework. A broker should be able to show how it prevents revenue from distorting customer outcomes.
A sustainable credit broking model can answer three questions without hesitation. Who pays the broker? Could that payment affect the options, recommendation or customer cost? What evidence shows the conflict is controlled and the customer understood the arrangement?
Clear answers make commission and fees easier to govern. Authorised Compliance helps credit brokers review remuneration, customer journeys and controls before gaps become regulatory problems.
This article provides general information, not advice on an individual firm's permissions or arrangements. Regulatory position checked on 24 September 2026.
I’m Will Hurst, and I bring 20+ years of hands-on experience across credit broking, AR/IAR oversight, lender relationships and regulated finance operations.
Learn more about my practical, FCA-focused approach
Specialist compliance support for UK credit brokers, Appointed Representatives and Introducer Appointed Representatives. We help firms build practical, FCA-aligned compliance frameworks covering customer journeys, financial promotions, AR/IAR oversight, Consumer Duty, complaints, monitoring and regulatory applications.
Services
FCA application supportAR and IAR supportCredit broker complianceWebsite and financial promotion reviewsConsumer Duty supportCompliance monitoringComplaints and customer outcome reviewsRegulatory remediation supportUseful links
HomeCredit Broker ComplianceAR & IAR SupportInsightsContactPrivacy PolicyCookie PolicyComplaints ProcedureTerms of BusinessContact
Email: support@authorisedcompliance.com
Office address: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Registered office: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Authorised Compliance Ltd is a company incorporated in England and Wales with registered company number 15833435.
Authorised Compliance Ltd is authorised and regulated by the Financial Conduct Authority under Firm Reference Number 1025416.
Registered with the Information Commissioner’s Office under reference ZB802407.