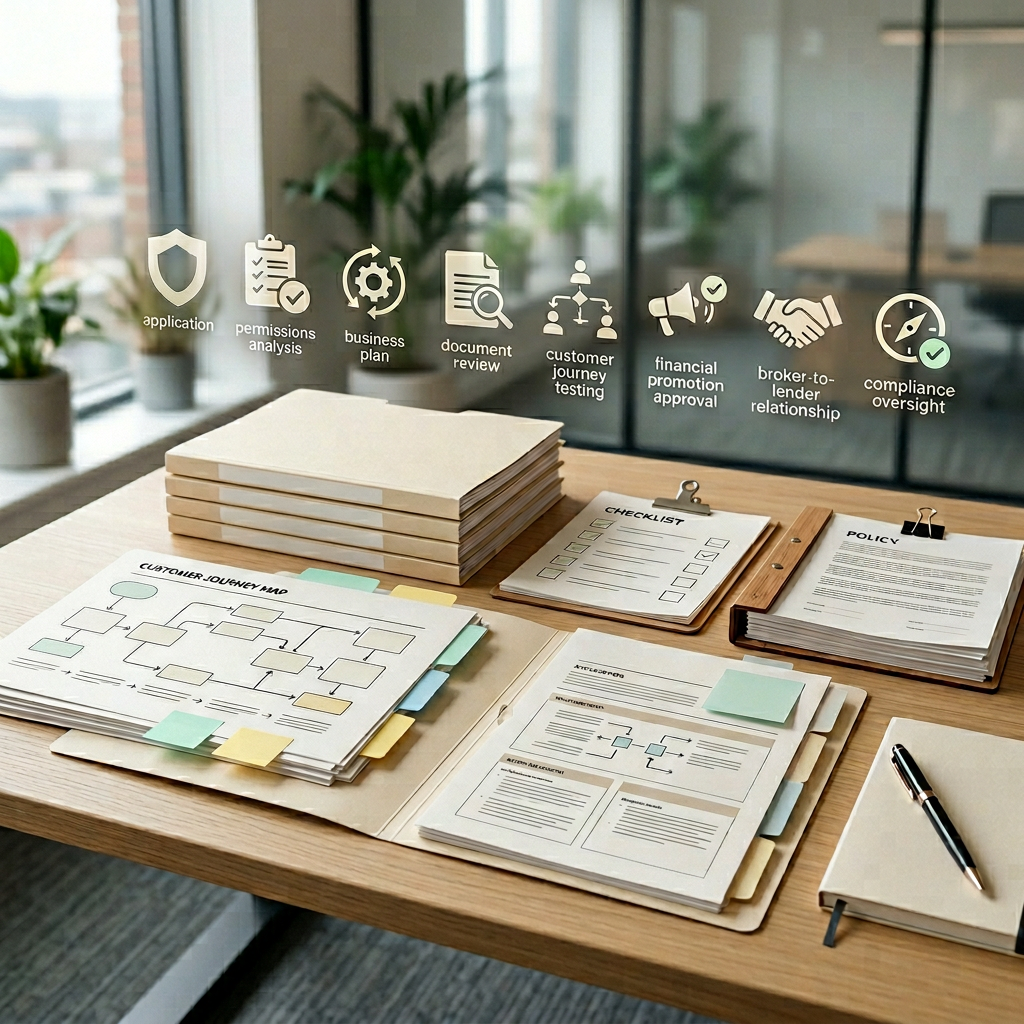
Reduce avoidable application rework by aligning your business model, supporting documents and answers to FCA questions. This guide covers preparation and response handling; it cannot predict an FCA decision or approval date.
For the submission sequence, use our step-by-step authorisation guide. This article focuses on inconsistencies, missing evidence and managing follow-up questions.
Use a working log for each FCA question: the exact request, response owner, requested date, evidence file and version, proposed answer, internal check and submitted response. Cross-check the answer against your application, financial information and customer journey before sending it. This is a suggested working method, not an FCA-prescribed template.
Common causes of delays include:
Many delays can be avoided by preparing the operating model properly before submission.
For related mistakes, read Common Compliance Mistakes Credit Brokers Make and How to Avoid Them.
The FCA may ask questions during the application process.
These may relate to:
Responses should be clear, accurate and consistent with the application documents.
If the firm changes its position in response to questions, the supporting documents should be updated so the application remains consistent.
The application should be built around a clear business model.
Before preparing documents, the firm should be able to explain:
A vague or inconsistent model can lead to delays. The FCA will need to understand how the business operates in practice.
For background on the broker role, read Credit Broker vs Lender: Key Differences Explained.
The permissions requested should match the activity being carried out.
Credit brokers should avoid applying for permissions that are too broad, too narrow or inconsistent with the business model.
A permissions review should consider:
The cheapest or quickest route is not always the right one. If the permissions do not match the activity, the firm may face problems after authorisation.
For a practical explanation of route options, read Choosing an FCA regulatory route for your credit broking firm.
The customer journey is a central part of a credit broking application.
It should show how customers move from first contact to outcome.
Review:
Customers should understand who they are dealing with, whether the firm is a broker or lender, what happens after enquiry and who makes the lending decision.
The journey should be reviewed before the application is submitted, not after FCA questions arrive.
The FCA will want to understand who is responsible for the business and whether the firm has appropriate skills and controls.
Prepare information on:
The firm should show that compliance responsibility is clear and that senior people receive useful information about risk.
The cost of navigating the FCA application process can include more than the FCA application fee.
Firms may need to budget for:
For more on costs, read How Much Does It Cost to Become an FCA Authorised Credit Broker?.
Authorised Compliance supports UK credit brokers with practical FCA application assistance.
Our support can include:
We focus on practical credit broking compliance, not generic application support. The aim is to help firms choose the right route and build a controlled, commercially workable operating model.
You can read more in How Authorised Compliance Helps Credit Brokers Stay FCA-Compliant and Choosing the Right FCA Compliance Consultant for Your Credit Broking Business.
Check the current requirements against the activity, customer, agreement and permissions of the particular firm. These primary sources support a scope and control review; a generic checklist does not establish compliance in every model.
No. Clear evidence supports assessment but does not determine the FCA's decision.
Establish the intended model, correct the inconsistency and check every affected document before responding.
Do not assume authorisation or a fixed decision date. Plan for unresolved questions and confirm the permission actually granted before regulated activity starts.
Explore our FCA application support and AR and IAR route support, or contact Authorised Compliance to discuss the work your application needs.
I’m Will Hurst, and I bring 20+ years of hands-on experience across credit broking, AR/IAR oversight, lender relationships and regulated finance operations.
Learn more about my practical, FCA-focused approach
Specialist compliance support for UK credit brokers, Appointed Representatives and Introducer Appointed Representatives. We help firms build practical, FCA-aligned compliance frameworks covering customer journeys, financial promotions, AR/IAR oversight, Consumer Duty, complaints, monitoring and regulatory applications.
Services
FCA application supportAR and IAR supportCredit broker complianceWebsite and financial promotion reviewsConsumer Duty supportCompliance monitoringComplaints and customer outcome reviewsRegulatory remediation supportMeta advertising supportAuthRouteLead generators, affiliates & publishersUseful links
HomeCredit Broker ComplianceAR & IAR SupportInsightsContactPrivacy PolicyCookie PolicyComplaints ProcedureTerms of BusinessContact
Email: support@authorisedcompliance.com
Office address: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Registered office: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Authorised Compliance Ltd is a company incorporated in England and Wales with registered company number 15833435.
Authorised Compliance Ltd is authorised and regulated by the Financial Conduct Authority under Firm Reference Number 1025416.
Registered with the Information Commissioner’s Office under reference ZB802407.