
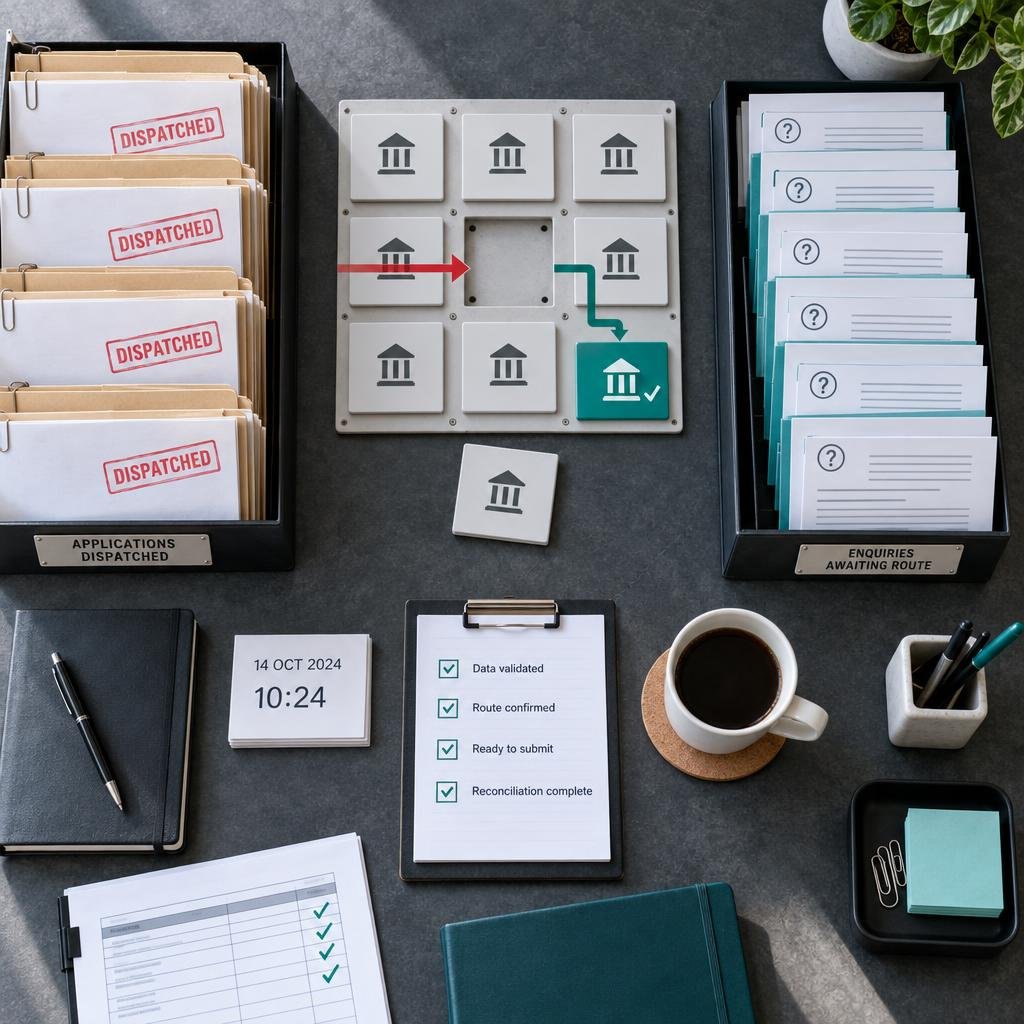
A lender leaving a credit broker's panel can look like a commercial problem: remove one destination, select another and carry on. For customers already moving through the journey, it is more serious than that.
Some enquiries may already be sitting with the departing lender. Others may be held in the broker's system but not yet transmitted. New enquiries may still be arriving through adverts, forms, affiliates or appointed representatives that describe a panel which has just changed.
The compliance risk sits in those differences. A hurried reroute can create duplicate applications, unexpected data sharing, inaccurate customer messages, avoidable delays and claims about lender access that are no longer true.
There is no single FCA-prescribed template for a lender-panel exit. The practical controls below are Authorised Compliance recommendations for managing the event in a way that supports applicable FCA and data-protection requirements.
The first question is not, "Who can take the volume?" It is, "Exactly what changed, and when?"
Record the time the lender stopped accepting new business, the products and customer groups affected, and any exceptions. Confirm whether the lender will continue processing applications already received, honour existing offers or agreements, return incomplete cases, or provide status data for reconciliation.
That information should come from an authorised lender contact or reliable contractual notice. Sales assumptions and informal messages are not enough to determine what customers should be told.
At the same time, stop new traffic reaching the obsolete route. Check more than the main integration. Manual submissions, spreadsheets, call-centre scripts, affiliate links, AR or IAR processes and retry queues can all keep sending cases after the headline route appears to be disabled.
Preserve the existing records. A routing freeze should not delete the evidence needed to establish what was submitted, when it was sent and what response came back.
The most useful immediate control is a clean split between:
Do not rely solely on the status label in the broker's CRM. Reconcile outbound records with lender acknowledgements, API responses, portal references or another reliable receipt. An enquiry marked "sent" without evidence of receipt may need different treatment from one the lender has accepted into its workflow.
It is also sensible to identify a third boundary: cases where a customer has already entered into a credit agreement. A lender's departure from the broker's panel does not, by itself, replace or transfer that agreement. Those customers should not be described as awaiting rerouting merely because the commercial panel has changed.
For each submitted enquiry, establish:
A second submission should not be the automatic response to uncertainty. Sending the same case elsewhere may expose the customer to duplicate contacts, repeated searches, inconsistent outcomes or a use of their data they did not expect. It may also make it harder to explain who is currently assessing the enquiry.
If an alternative route is being considered, the broker should first understand the status of the original submission and assess the contractual, regulatory and data-protection position. The customer communication should explain what has happened, whether another lender has received or may receive their information, and whether the customer needs to make a decision or provide anything further.
A lender-panel exit is not the same as a decline. Firms should not tell a customer that an application was refused if the lender simply stopped accepting or processing that category of business. The status description must reflect the verified facts.
Unsubmitted enquiries may be easier to control, but they should not be poured into the next available route without review.
Before activating a replacement lender, check that:
Under CONC 3, relevant communications and financial promotions must be clear, fair and not misleading. Credit brokers must also describe their role and lender relationships accurately. A statement that the firm works with a particular panel, searches a broad market or acts independently must continue to reflect the real service after the change.
Where the existence or amount of commission could affect the broker's impartiality, or materially affect the customer's decision if known, CONC 4.5 contains relevant disclosure requirements. A replacement route that changes remuneration or product ranking therefore needs more than a technical integration check.
A new lender is a new recipient, or at least a change in how the customer's information is being used. The broker should verify the intended purpose, lawful basis, data minimisation and privacy information before sharing.
Consent is not the only possible lawful basis, and it is not automatically the correct one. The point is to identify and document the lawful basis that actually applies. The ICO says organisations must identify a lawful basis before sharing personal data and be able to show that they considered it.
Customers should also receive clear information about the purposes for which their data is used and the recipients or categories of recipients. Where the replacement route represents a new use that was not already explained, the ICO's transparency guidance says it should be brought to the individual's attention before the processing starts.
That review should cover forms, privacy notices, just-in-time wording, confirmation messages, call scripts and the data actually sent. It should not be reduced to adding another lender name to a long list without considering what the customer reasonably understood when they supplied their information.
The Consumer Duty applies according to the regulatory perimeter and the firm's role. Where it applies, PRIN 2A requires firms to support customer understanding with information that is timely, clear and capable of supporting informed decisions. It also requires firms to avoid causing foreseeable harm and provide appropriate support.
A lender exit can produce several different messages, not one blanket template. A useful communication should make clear:
The communication should not promise acceptance, imply that a replacement lender will offer equivalent terms, or suggest the broker controls the lending decision. It should distinguish the broker's role from the lender's role and use the status that the firm can evidence.
The transition is not contained if the central system changes while customer-facing material continues to describe the old panel.
Review:
SYSC 3.1.1R requires a firm within scope to take reasonable care to establish and maintain systems and controls appropriate to its business. The FCA's guidance recognises that the nature and extent of those controls depend on the scale, complexity, volume and risk of the operation. A small broker may not need a complex incident platform, but it still needs a reliable way to control the change and demonstrate what happened.
The event is not complete when the new route is switched on. It is complete when the firm has reconciled the affected cases, corrected the customer journey and reviewed the resulting outcomes.
Authorised Compliance recommends a transition record that captures:
These are practical controls, not a fixed FCA checklist. The evidence selected should be proportionate to the business and capable of showing whether customers experienced avoidable delay, confusion or harm.
A lender departure exposes whether the broker genuinely understands its customer journey. It tests the accuracy of panel claims, the reliability of routing data, the clarity of privacy information, the quality of customer communications and the firm's ability to monitor outcomes across commercial partners.
The most defensible response is not to move every case as quickly as possible. It is to establish where each enquiry sits, control what happens next and keep customers informed with facts the firm can support.
For credit brokers, principal firms and AR or IAR networks, that discipline turns a sudden commercial change into a controlled transition rather than a trail of unexplained handoffs.
Authorised Compliance supports credit brokers with customer-journey reviews, lender-panel controls, Consumer Duty assessments, financial-promotion reviews, AR and IAR oversight, monitoring and remediation planning.
I’m Will Hurst, and I bring 20+ years of hands-on experience across credit broking, AR/IAR oversight, lender relationships and regulated finance operations.
Learn more about my practical, FCA-focused approach
Specialist compliance support for UK credit brokers, Appointed Representatives and Introducer Appointed Representatives. We help firms build practical, FCA-aligned compliance frameworks covering customer journeys, financial promotions, AR/IAR oversight, Consumer Duty, complaints, monitoring and regulatory applications.
Services
FCA application supportAR and IAR supportCredit broker complianceWebsite and financial promotion reviewsConsumer Duty supportCompliance monitoringComplaints and customer outcome reviewsRegulatory remediation supportUseful links
HomeCredit Broker ComplianceAR & IAR SupportInsightsContactPrivacy PolicyCookie PolicyComplaints ProcedureTerms of BusinessContact
Email: support@authorisedcompliance.com
Office address: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Registered office: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Authorised Compliance Ltd is a company incorporated in England and Wales with registered company number 15833435.
Authorised Compliance Ltd is authorised and regulated by the Financial Conduct Authority under Firm Reference Number 1025416.
Registered with the Information Commissioner’s Office under reference ZB802407.