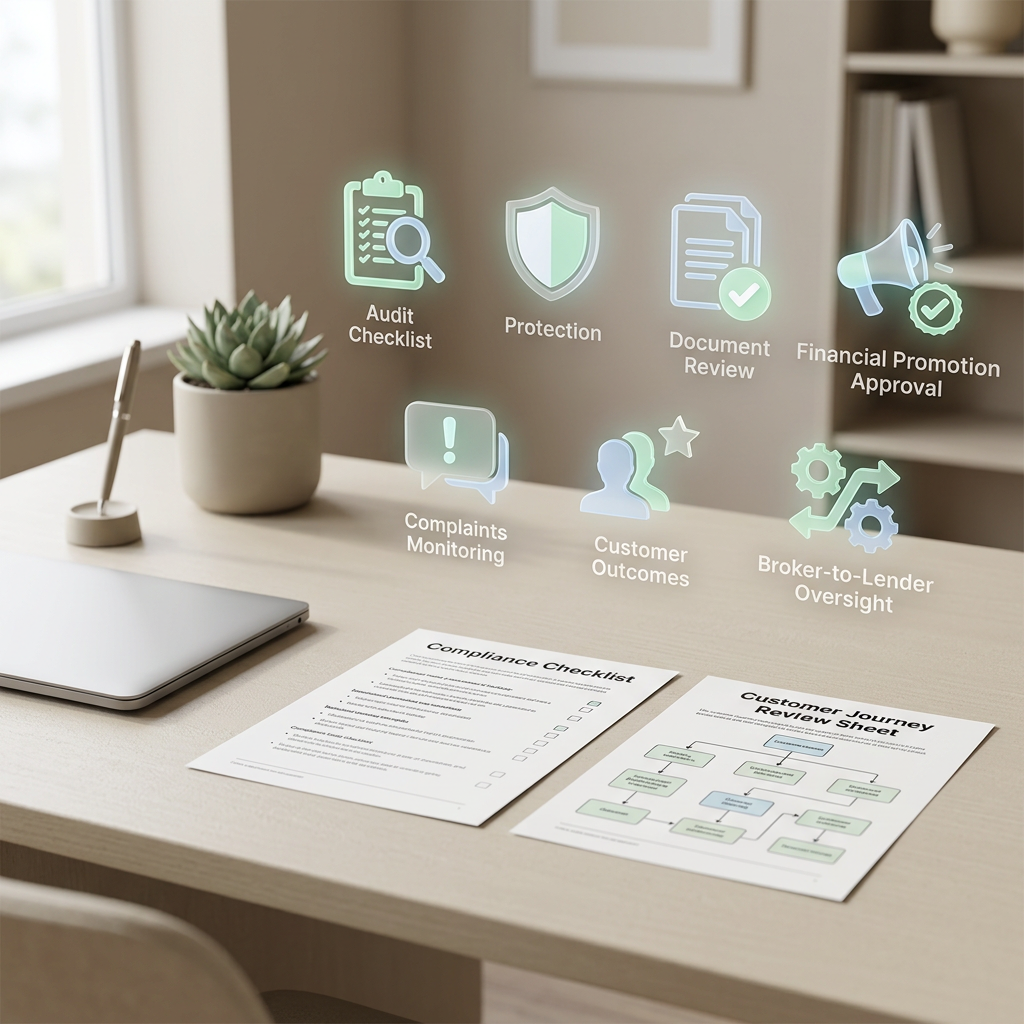
A compliance audit examines how controls work and what the evidence shows. Agree the scope and reviewer, prepare representative records, discuss findings and track corrective action. The process depends on who commissions the review.
Confirm the reviewer, purpose, activities, period and expected output. A principal review, an independent audit and an FCA request have different authority and scope. The practical steps here describe a typical review, not a mandatory FCA audit sequence.
Agree how files, calls and customer journeys will be selected. Include exceptions and adverse outcomes as well as routine cases. Record the selection method and limitations so findings are not presented as proof about untested activity. Interviews can explain how work is done; test those explanations against records.
For each finding, identify the evidence, affected control, consequence, owner and target date. Separate factual disagreements from agreed actions. Recheck the corrective action before closing it and retain the supporting record.
Use our regulatory evidence-pack guide for assembling a response and our working compliance checklist for routine monitoring.
An FCA compliance audit is a review of whether a regulated firm is operating in line with its permissions, obligations and customer outcome expectations.
For credit brokers, a review may look at how the firm:
Not every review will look the same. The scope may depend on the firm’s business model, risk profile, permissions, complaints, growth, marketing activity, AR/IAR arrangements or previous issues.
For a broader overview of the compliance framework, read What Is Credit Broking Compliance? A Beginner’s Guide.
A credit broker may face different types of compliance review.
This could include:
The reviewer may differ, but the evidence needed is often similar. A firm should be able to show how it controls the activity it carries out.
A credit broker should be prepared to provide evidence such as:
The exact request will depend on the scope of the review, but a firm that keeps good records will be in a stronger position.
Preparation should start before any formal request arrives.
Useful steps include:
For a practical checklist, read Credit Broking Compliance Checklist: What You Need to Know.
After a review, the firm may receive findings, recommendations or requests for further information.
Actions may include:
The most important point is to act on findings. A review is much less valuable if issues are identified but not followed through.
For more on regulatory checks, read Preparing for FCA regulatory checks: a credit broker evidence guide.
Common mistakes include:
These issues are avoidable with regular monitoring and clear ownership.
For more detail, read Common Compliance Mistakes Credit Brokers Make and How to Avoid Them.
Authorised Compliance supports UK credit brokers with FCA audit and regulatory review preparation.
Our support can include:
We help firms identify gaps, organise evidence and build practical controls that support day-to-day credit broking activity.
You can read more in How Authorised Compliance Helps Credit Brokers Stay FCA-Compliant and Choosing the Right FCA Compliance Consultant for Your Credit Broking Business.
Check the current requirements against the activity, customer, agreement and permissions of the particular firm. These primary sources support a scope and control review; a generic checklist does not establish compliance in every model.
No. Confirm who commissions and conducts the review. A principal or independent review is different from a review conducted by the FCA.
No. Record the selection method and limits. Investigate whether findings indicate a wider issue rather than assuming untested files are satisfactory.
Record the agreed correction and supporting evidence, then check that the action addressed the finding. A completed task alone does not show that the control works.
See our compliance monitoring support or discuss an audit or review-preparation scope with Authorised Compliance.
I’m Will Hurst, and I bring 20+ years of hands-on experience across credit broking, AR/IAR oversight, lender relationships and regulated finance operations.
Learn more about my practical, FCA-focused approach
Specialist compliance support for UK credit brokers, Appointed Representatives and Introducer Appointed Representatives. We help firms build practical, FCA-aligned compliance frameworks covering customer journeys, financial promotions, AR/IAR oversight, Consumer Duty, complaints, monitoring and regulatory applications.
Services
FCA application supportAR and IAR supportCredit broker complianceWebsite and financial promotion reviewsConsumer Duty supportCompliance monitoringComplaints and customer outcome reviewsRegulatory remediation supportMeta advertising supportAuthRouteLead generators, affiliates & publishersUseful links
HomeCredit Broker ComplianceAR & IAR SupportInsightsContactPrivacy PolicyCookie PolicyComplaints ProcedureTerms of BusinessContact
Email: support@authorisedcompliance.com
Office address: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Registered office: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Authorised Compliance Ltd is a company incorporated in England and Wales with registered company number 15833435.
Authorised Compliance Ltd is authorised and regulated by the Financial Conduct Authority under Firm Reference Number 1025416.
Registered with the Information Commissioner’s Office under reference ZB802407.