
A commercial finance broker prepares a perfectly ordinary Meta campaign.
The advert is aimed at company directors. The landing page discusses working capital, asset finance or commercial mortgages. The proposed borrowers are limited companies. Nothing is being offered for personal, family or household purposes.
The broker has considered the regulatory perimeter and concluded that the activity is not regulated consumer credit business. Then Meta rejects the advert because the advertiser cannot establish a connection to an FCA-authorised firm.
It is an odd moment. The product may sit outside FCA regulation, yet the route to advertising it appears to run straight through the FCA Register.
This is not necessarily a mistake by Meta. Nor does it mean the original perimeter analysis was wrong. It is the result of two different systems using two different tests for two different purposes.
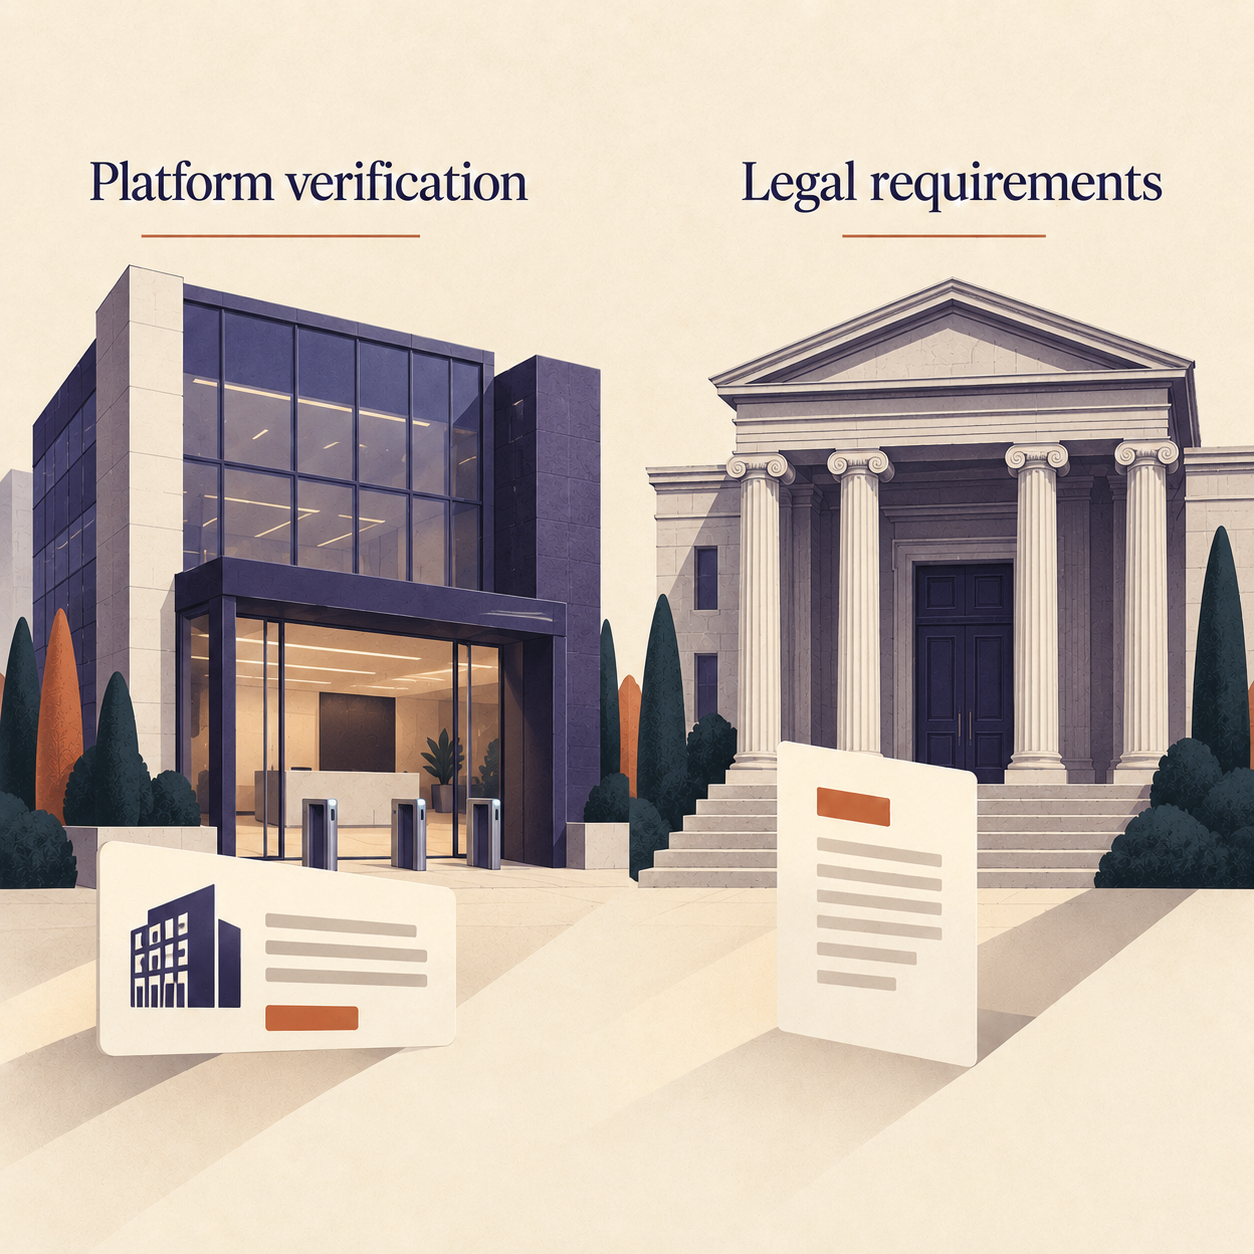
The law asks whether the particular product, borrower, agreement and activity fall within regulation. Meta asks whether an advertisement looks like financial services advertising and whether the organisation behind it can pass the platform’s verification controls.
One is a regulatory perimeter. The other is the admission policy of a private advertising platform.
Confusing the two can leave legitimate commercial finance firms unable to advertise. Worse, it can lead businesses into unsuitable arrangements with regulated entities merely to obtain access to an advertising account.
The starting point is that commercial lending is commonly outside the FCA’s remit. The FCA itself lists commercial mortgages and lending among the products and services it does not regulate or supervise.
That statement, however, is a useful summary rather than a universal exemption for anything carrying the word “business”.
Regulatory status can depend on who is borrowing, the purpose of the credit, the amount involved, how the agreement is structured, whether security is taken over land and what the intermediary actually does.
A straightforward loan to a limited company for its trading activity will normally present a different regulatory analysis from credit offered to a sole trader. A commercial mortgage over business premises raises different questions from borrowing secured against a home. An advert written solely for business borrowing may also be treated differently from one whose wording allows personal borrowing to slip quietly through the side door.
The FCA Handbook recognises an exemption for certain financial promotions relating to credit for business purposes. As explained in PERG 8.17-A.10G, article 46A of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 covers communications relating to specified lending, consumer-hire and electronic lending-system activities. It is not a blanket exemption for adverts promoting credit-broking services, which must be assessed separately. The communication must clearly concern credit for another person’s business and must not suggest availability for other purposes; the advertiser’s or broker’s own business is not the relevant business for this exemption. The conditions matter. “Business finance” in the headline will not necessarily rescue a wider customer journey that also invites personal applications.
CONC 3 similarly excludes from much of its scope a promotion that clearly indicates, expressly or by implication, that it is solely promoting credit agreements for a customer’s business. Again, “solely” is doing some work.
The regulatory perimeter therefore requires analysis. It does not respond well to slogans.
Meta’s systems have a less delicate task. They must examine enormous volumes of advertising, identify financial content, prevent impersonation and scams, and make decisions quickly enough for an advertising market that operates in real time. A machine reviewing an advert promising “funding in 24 hours” cannot conduct a legal conference about borrower constitution and the meaning of business purpose.
So Meta uses broad categories and identity checks.
The result is a deliberate mismatch. A product may be unregulated under UK financial services law but still be treated as financial services advertising under Meta’s rules.
This is the distinction every broker, lender, marketing agency and principal should put at the top of the campaign brief.
Meta verification and FCA approval are not the same thing.
Meta’s UK controls require advertisers promoting financial products or services to establish an appropriate connection to an FCA-authorised or registered firm. Meta introduced its UK policy in late October 2022 following sustained pressure on online platforms to prevent fraudulent financial advertising. The FCA has since described the policies of major platforms as allowing UK financial services advertising only by FCA-authorised firms or where advertisements have been approved by an authorised firm.
Meta has also told Parliament that advertisers wishing to promote financial services products to UK users must first be registered with the FCA and have that status verified.
In practice, verification can involve the firm’s FCA Firm Reference Number and contact details associated with its regulatory record. The purpose is broadly to show that the advertiser is genuinely connected to the regulated organisation it claims to represent.
That is a platform identity and eligibility control. It is not a declaration by the FCA that:
Nor does Meta’s acceptance of an advert settle any of those questions. Meta decides whether content may appear on Meta. It does not issue legal opinions on the UK regulatory perimeter.
The phrase “signed off by a regulated entity” can therefore conceal several different propositions.
It might mean that an authorised firm has permitted an advertiser to use a Meta verification route. It might mean the firm has reviewed the copy under a contractual compliance process. It might mean a principal has approved a promotion used by its appointed representative. In a genuinely regulated case, it might mean formal approval of a financial promotion for the purposes of section 21.
Those arrangements carry different legal consequences. Treating them as interchangeable is an invitation to trouble.
Section 21 of the Financial Services and Markets Act 2000 restricts an unauthorised person from communicating an invitation or inducement to engage in investment activity unless the communication is made or approved by an authorised person, or an exemption applies.
That is the statutory financial promotion restriction. It is serious. Breach can be a criminal offence.
But it does not follow that every advert Meta categorises as “financial services” is automatically a section 21 financial promotion requiring statutory approval.
A promotion relating only to commercial lending may fall outside the relevant controlled activities or meet an applicable business-purpose exemption. If so, the legal requirement for section 21 approval may not arise even though Meta still refuses to carry the advert without FCA-linked verification.
This is where language matters.
An authorised firm reviewing such an advert should not casually record that it has given “section 21 approval” without first establishing that section 21 applies. Equally, an unregulated broker should not tell customers that its commercial finance products are “FCA approved” simply because an authorised firm helped it satisfy Meta’s onboarding process.
There is no regulatory prize for applying the wrong legal label with great confidence.
The distinction has become more important since the financial promotion approval gateway took effect on 7 February 2024. An authorised firm generally cannot approve promotions for unauthorised persons unless it has the relevant permission to do so or an exemption from the gateway applies. Exemptions can include certain promotions prepared by the firm itself, another member of its group or its appointed representative in connection with the business for which the principal has accepted responsibility.
The gateway should therefore be considered whenever actual section 21 approval is proposed. It should not be bypassed by describing a third-party arrangement as “marketing support”, “platform access” or a quick favour with an FRN attached.
At the same time, firms should avoid manufacturing a statutory approval exercise where none is legally needed. The better approach is to document separately:
The paperwork may be less exciting than the campaign creative. It is also much more useful when someone later asks why an FCA-authorised entity was involved in an advert for an unregulated product.
The policy makes more sense when viewed as an anti-fraud measure rather than a finely calibrated statement of UK regulatory law.
A fraudulent advertiser can copy a logo, company name, website design and Firm Reference Number within an afternoon. A platform cannot rely on the presence of an FRN in small print as evidence that the person buying the advert has anything to do with the firm concerned.
Meta’s verification process is intended to establish a connection between the advertiser and the regulated business. That creates friction for impersonators, although it does not guarantee that every fraudulent advert will be stopped or that every legitimate campaign will pass smoothly.
The FCA’s 2022 financial promotions data records that Meta, Instagram, TikTok, Twitter and Bing changed their policies following engagement with the regulator. The FCA also noted that it remained in discussion with Meta about how consistently the policy blocked illegal advertising.
The problem has not disappeared. In April 2026, the FCA said it had made 120 account takedown requests as part of an international operation against illegal finfluencer content. The Meta-specific material identified by the regulator included 1,267 illegal financial adverts which had reached at least 2.3 million UK accounts. Sixty-six per cent came from firms or individuals already on the FCA Warning List.
The verification gate is therefore neither pointless nor infallible. It is a coarse control aimed at a large and persistent problem.
The commercial finance broker caught by it is collateral inconvenience, not the policy’s intended target. Unfortunately, “we are legitimate” is not a technical solution. The firm still needs an operating model that can pass the platform’s controls.
The most dangerous response is to find an authorised firm willing to lend its regulatory identity without accepting meaningful responsibility.
That arrangement creates risk for everyone.
The advertiser may believe the authorised firm has validated its whole business. The authorised firm may think it has merely helped with Meta access. Meta may understand that the advertiser is legitimately connected to the regulated entity. Prospective customers may see regulatory language on the landing page and assume protections apply to the product.
Four parties can leave the same arrangement with four different ideas about what has happened.
A regulated firm should understand the advertiser’s business model before allowing its identity, permissions or verification status to support a campaign. That means looking beyond the image and headline.
The review should cover the target borrower, product range, proposed lenders, security, business-purpose criteria, lead-routing arrangements, remuneration and the point at which the customer may encounter a regulated product or activity.
It should also examine what happens after the click. A Meta advert leading to a commercial finance page can still produce regulated risk if the application journey accepts individuals, gathers information for personal borrowing or redirects unsuitable applicants into regulated credit without an appropriate framework.
A declaration that the borrowing is “for business purposes” is evidence. It is not a force field. The FCA’s guidance expressly recognises that a business-purpose declaration will not support the statutory presumption where the lender or someone acting for it knows, or has reasonable cause to suspect, that the borrowing is not wholly or predominantly for business purposes.
Customer reality outranks form wording.
Many perimeter problems begin with marketing copy that is wider than the product the compliance team thought it was reviewing.
The business model may be limited to incorporated companies, but the advert says “Funding for your next move”. The product team may intend working capital only, but the landing page offers money for “whatever matters to you”. A sole trader sees “business loan”, completes the form and is accepted into a journey designed around limited-company borrowers.
Marketing likes wide doors. Regulatory analysis prefers labelled ones.
If a firm intends to rely on a business-purpose analysis, the campaign should make that purpose clear throughout the journey. Audience targeting alone is not enough. Meta’s targeting tools do not turn ambiguous copy into a business-only promotion, and a user’s job title does not establish the legal purpose of a loan.
The advert, lead form, landing page, eligibility questions, telephone script and lender hand-off should all support the same perimeter conclusion.
That does not require an assault of legal wording. It requires precision.
“Business funding for UK limited companies” is more informative than “Cash when you need it”.
“Finance for equipment, stock and working capital” is more useful than “Turn your plans into reality”.
“Subject to status, eligibility and lender assessment” is more credible than “Approved today”.
Good advertising can still be energetic. It simply has to know what it is advertising.
Even where an advert falls outside FCA financial promotion rules, it does not enter a lawless zone.
The CAP Code contains rules for financial marketing communications not regulated by the FCA or Trading Standards. Among other things, such communications should be presented in a way that can be understood easily by the audience and must not take advantage of consumers’ inexperience or credulity.
General advertising law also continues to matter. Claims need substantiation. Material qualifications should not be hidden. Pricing must not be misleading. Data protection obligations apply to lead collection and subsequent contact. Meta imposes its own policies in addition to these requirements.
Commercial customers are not incapable of being misled merely because Companies House issued them a number.
A director under cash-flow pressure may be highly responsive to claims about speed, certainty and access to funds. An advert that says “guaranteed approval”, “no checks” or “funding for every business” should cause concern regardless of whether CONC technically applies.
The absence of FCA regulation is not permission to replace compliance with improvisation.
It also does not justify displaying an authorised firm’s status in a way that implies broader protection. Regulatory disclosures should identify which entity is authorised, the nature of its relationship with the advertiser and, where material, that the commercial finance product itself is not regulated by the FCA.
The wording will depend on the actual model. A generic footer copied from another website is not analysis.
A workable arrangement starts with classification, not creative approval.
Before a campaign is submitted, the business should identify the proposed borrower population, the use of funds, the product structure and the activities performed by every participant. Edge cases should be resolved deliberately. Sole traders, small partnerships, mixed-purpose borrowing, second-charge security, buy-to-let and referrals into personal credit should never be allowed to drift through an SME funnel unnoticed.
The relationship with the regulated entity must then be defined.
Is the advertiser an appointed representative whose principal has accepted responsibility for relevant activity? Is it an introducer appointed representative operating within a tightly restricted remit? Is it an unregulated commercial finance business using services supplied by an authorised firm? Is the authorised firm actually approving a regulated promotion, or only supporting platform verification and conducting a non-statutory advertising review?
The answer controls the governance.
The authorised firm should have contractual rights over the use of its name, FRN and Meta verification. It should be able to approve, reject, withdraw and monitor campaigns. It should know which Pages, Business Portfolios, ad accounts, domains and agencies are involved. Access should be removed promptly when the relationship ends.
Each campaign should have a review record containing the final advert, creative, landing page, lead form and material customer communications. Version control matters because an approval for one headline should not become a lifetime licence for the marketing team to “test a few punchier variants”.
Monitoring should continue after launch. Comments, complaints, lead quality, applicant type, decline reasons and customer misunderstandings can reveal that a supposedly business-only promotion is attracting the wrong audience. Cheap leads are not a triumph if half of them expose a flaw in the perimeter analysis.
Meta status should also be checked operationally. The legal entity, trading name, website, contact details and advertising assets should form a coherent picture. Where an appointed representative is involved, the principal’s compliance team should confirm the verification route rather than allowing an agency to guess which FRN will make the form accept the submission.
Authorised Compliance Ltd approaches financial promotion reviews in this wider way. The words in the advert matter, but so do the customer journey, the permissions, the parties involved, the evidence of review and what happens to the lead afterwards. That is particularly important for commercial finance campaigns, where the boundary between regulated and unregulated activity can depend on facts that never fit neatly into a social media image.
For firms that need practical help with the platform process, see our Meta advertising support for commercial finance firms.
Meta did not bring commercial lending within the FCA perimeter. It does not have that power.
What it has done is create a distribution condition. For many firms, access to a significant advertising channel now depends on an FCA-linked verification route even where the promoted product is unregulated.
That condition can be commercially decisive. A perfectly lawful business model may struggle to acquire customers if it cannot advertise through the platforms on which those customers spend their time. Platform governance has therefore acquired a regulatory flavour without becoming regulation itself.
There is a temptation to complain about the contradiction. Some complaint is justified. Broad anti-fraud controls can exclude legitimate firms, and opaque rejection processes do not become charming merely because the underlying policy has a worthy objective.
But the more useful response is to understand the distinction and build for it.
Do not claim that a commercial finance product is regulated merely because Meta wants to see an authorised firm. Do not assume that “unregulated” means no review is needed. Do not borrow an FRN from a friendly business and hope nobody asks what the relationship involves.
Meta’s gate and the FCA’s perimeter are separate. A credible commercial finance operation must be able to explain both.
The strangest part of the arrangement is also the most revealing. In modern financial services, permission to reach the market may come from somewhere other than the law. The compliance work begins by knowing whose permission it is, what it means and, just as importantly, what it does not.
No. Meta verification concerns access to its advertising platform. It does not establish FCA approval of the advert, product or advertiser’s activities.
No. Assess the borrower, product, activity and communication. Article 46A has specific activity and business-purpose conditions; it is not a blanket exemption for credit-broking promotions.
Do not treat another firm’s FRN as a shortcut. Confirm the genuine relationship, permitted use of its identity and Meta’s applicable verification requirements before submitting the campaign. Account-specific steps should be checked in Meta’s current verification flow.
I’m Will Hurst, and I bring 20+ years of hands-on experience across credit broking, AR/IAR oversight, lender relationships and regulated finance operations.
Learn more about my practical, FCA-focused approach
Specialist compliance support for UK credit brokers, Appointed Representatives and Introducer Appointed Representatives. We help firms build practical, FCA-aligned compliance frameworks covering customer journeys, financial promotions, AR/IAR oversight, Consumer Duty, complaints, monitoring and regulatory applications.
Services
FCA application supportAR and IAR supportCredit broker complianceWebsite and financial promotion reviewsConsumer Duty supportCompliance monitoringComplaints and customer outcome reviewsRegulatory remediation supportMeta advertising supportUseful links
HomeCredit Broker ComplianceAR & IAR SupportInsightsContactPrivacy PolicyCookie PolicyComplaints ProcedureTerms of BusinessContact
Email: support@authorisedcompliance.com
Office address: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Registered office: Atlantic Business Centre, Atlantic Street, Broadheath, Altrincham, England, WA14 5NQ
Authorised Compliance Ltd is a company incorporated in England and Wales with registered company number 15833435.
Authorised Compliance Ltd is authorised and regulated by the Financial Conduct Authority under Firm Reference Number 1025416.
Registered with the Information Commissioner’s Office under reference ZB802407.